Last updated: November 9, 2026
Financial planning for physicians should change as income, benefits, debt, family responsibilities and career goals change. A resident may need to protect cash flow and future earning capacity. An attending physician, surgeon or practice owner may need closer coordination among taxes, retirement accounts, insurance, investments, asset protection and estate priorities. A physician’s financial plan should evolve with each career transition.
In financial planning for physicians, timing matters: doctors often go through several financial changes in a short period. Training delays full earnings. Income then rises quickly. Employer benefits change with each job move, while student loans, family priorities, insurance and retirement saving compete for the same cash flow.
A useful financial plan doesn’t treat these decisions separately. It sets which priorities deserve attention now, which can wait, and how each choice affects the rest of the picture. This guide walks through financial planning for physicians and doctors stage by stage, with the questions to ask at each point.
Why physicians need a different kind of financial plan
Financial planning for physicians starts with the same goals as anyone else’s, but the path is shaped by a few things that are unusual about medicine:
- A late start. Years of medical school, residency and fellowship mean full earnings often begin in your 30s, leaving fewer high-income years to save for retirement.
- Large education debt that arrives before the income to repay it.
- A fast income jump after training, which makes it easy to build a lifestyle before building a plan.
- High tax exposure once income rises, and income limits that can restrict some account types.
- Income that depends on your ability to practice, which makes disability coverage and liability protection central to the plan.
- Little spare time. Long hours and call schedules make it easy to postpone reviews for years.
How financial priorities change across a medical career
Your career stage affects how much flexibility you have, which risks matter most and how long your money has to support future goals. A resident and an established practice owner may both want to build wealth, but they face different immediate decisions. The same action can also have different effects at different stages. Paying debt aggressively may make sense when interest costs are high and cash flow is stable, but it may cause problems if it leaves too little cash for an upcoming move, a practice buy-in or a gap between employers.
| Career stage | Common financial focus | Questions to review |
|---|---|---|
| Medical school, residency and fellowship | Cash flow, student loans, emergency reserves, disability coverage | How much liquidity do I need? Which decisions can wait until my income changes? |
| Early attending years | Income allocation, workplace benefits, debt repayment, insurance, investing | Where should the next dollar go? Which benefits should I use first? |
| Midcareer | Retirement progress, family goals, tax coordination, investment risk | Are my financial decisions working together? Has lifestyle growth reduced my savings capacity? |
| Practice ownership or leadership | Business cash flow, benefits, insurance, liability, personal concentration risk | Which risks belong to the practice, and which belong to my personal plan? |
| Approaching retirement | Retirement timing, income planning, healthcare coverage, portfolio risk | Can my resources support the life I expect after medicine? |
For a list of specific items to check at each stage, see our financial checklist for medical professionals. This guide explains how those decisions connect.
1. Let income progression set the pace of the plan
A higher income creates more options, but it doesn’t automatically create clarity. Moving from a trainee salary to an attending salary can make many goals look affordable at once: paying off loans faster, buying a home, increasing retirement contributions, replacing a car, expanding insurance, funding education and investing outside workplace accounts.
The goals aren’t the problem. Funding all of them at once can create fixed expenses that reduce flexibility later.
Build a repeatable allocation process
Instead of treating every raise or bonus as spending money, decide how extra income will be divided before it arrives. A practical order might consider:
- Required expenses and minimum debt payments
- A suitable emergency reserve
- Employer retirement plan benefits, such as a match
- High-cost debt
- Insurance and risk-management gaps
- Other retirement contributions
- Near-term family or career goals
- Additional investing or faster debt repayment
This order is not a universal recommendation. Your priorities depend on loan terms, available benefits, household income, taxes and upcoming expenses. The important point is to have an order. Without one, the most visible or urgent request usually gets the money.
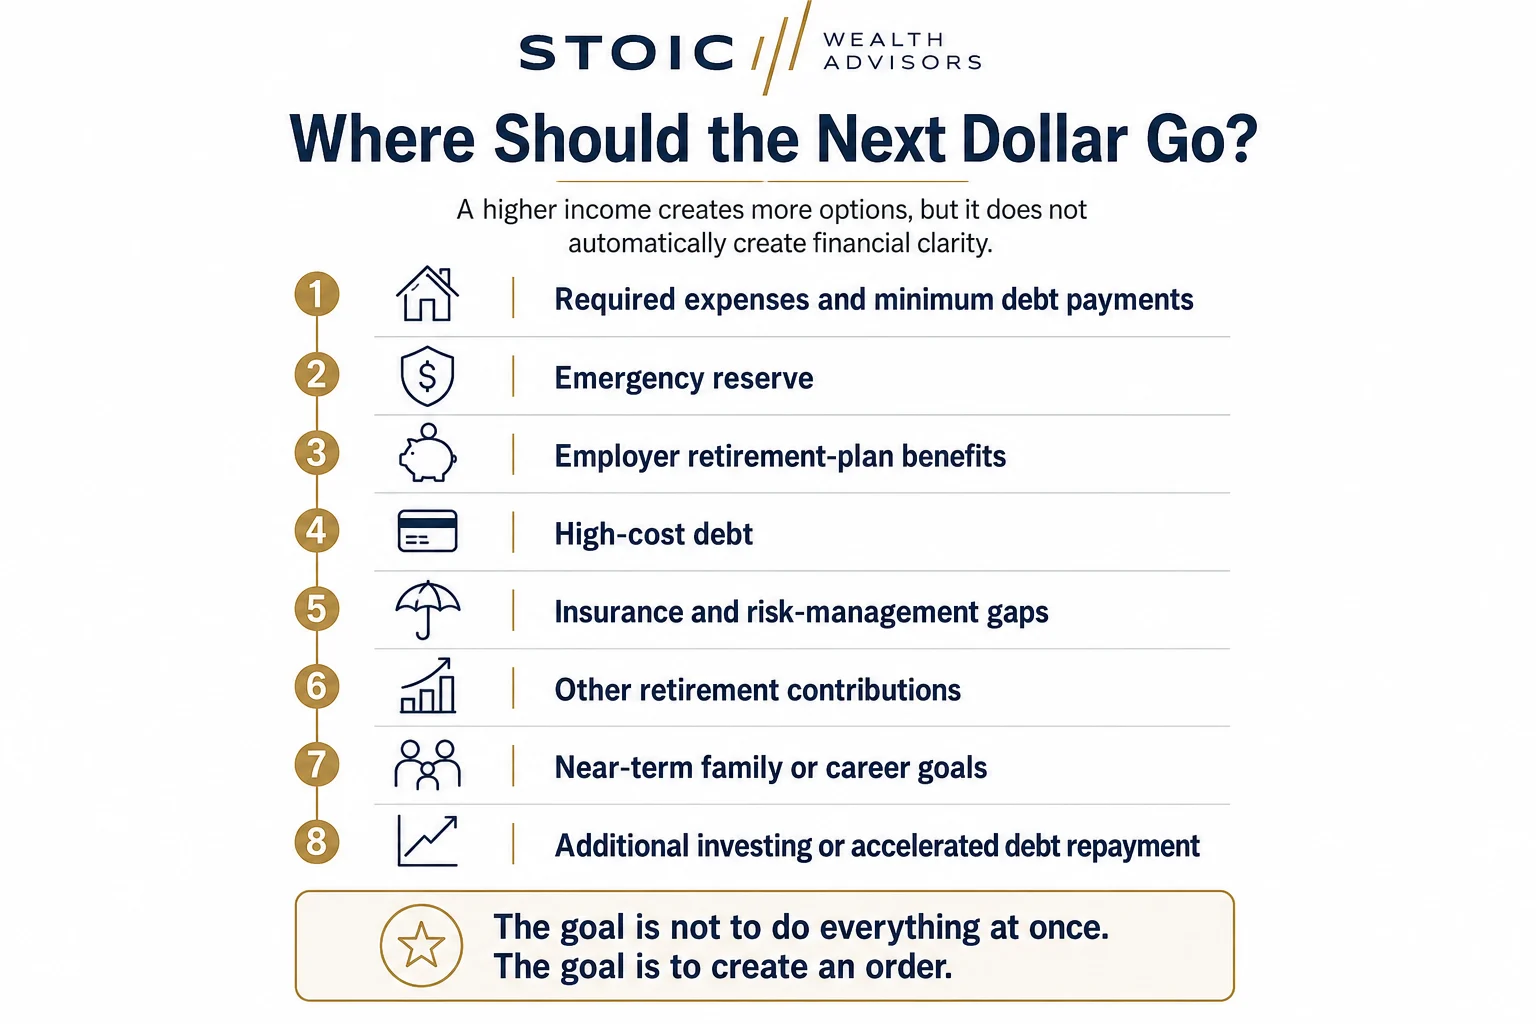
A higher income gives physicians more options, but a clear priority order helps prevent scattered financial decisions.
Avoid building a lifestyle around peak income
Physician income can vary with bonuses, RVU or productivity pay, call schedules, practice revenue and job changes. Build recurring expenses around the income you can reasonably expect, and treat variable income as a planning resource, not money that must support a bigger lifestyle right away. This matters even more if you’re considering practice ownership, part-time work, a change of specialty or an early retirement.
2. Student loans, cash reserves and investing compete for the same dollar
Repaying debt versus investing is rarely all-or-nothing. Paying loans faster can cut interest costs and bring relief. Investing can support long-term goals and give money more time to grow. Cash reserves protect both, so you don’t have to borrow or sell investments in an emergency.
Know whether loan forgiveness applies to you
Many physicians train and work at non-profit hospitals or government employers. The federal Public Service Loan Forgiveness (PSLF) program forgives the remaining balance on Direct Loans after the equivalent of 120 qualifying monthly payments under an accepted repayment plan, while working full time for an eligible employer (StudentAid.gov). If PSLF could apply to you, it changes the math on paying loans down early, so confirm your loan types and employer eligibility before deciding.
The right balance also depends on interest rates and terms, employer retirement contributions, emergency savings, income stability, upcoming purchases or job changes, tax treatment, your comfort with debt and the time left before retirement.
Protect liquidity before eliminating every debt
A physician can have a high income and a strong net worth and still face a cash-flow problem if most assets are hard to reach. Before sending every spare dollar to loans, consider expenses that may come up over the next one to three years, such as relocation, parental leave, a home purchase, a practice buy-in, tax payments or time between jobs. The right reserve changes over a career. A dual-income household with stable jobs may need a different buffer than a solo practice owner with variable revenue.
Compare the certain cost with the uncertain return
Debt interest is a contractual cost. Investment returns are uncertain. That doesn’t mean every debt must be cleared before investing. It means the comparison should account for the cost of the debt, the repayment period, the value of employer contributions, your time horizon, the investment risk and your need for accessible cash. A good plan shows the trade-off instead of declaring one answer automatically better.
3. Treat workplace benefits as part of your compensation
Salary doesn’t show the full value of an offer. Retirement plans, insurance, paid leave, vesting schedules and health coverage can change the comparison. Hospitals and physician groups may offer a 401(k), a 403(b), a 457(b) or another arrangement. The IRS explains that a 401(k) lets employees defer part of their wages into individual accounts, while 403(b) plans can be offered by public schools and certain tax-exempt organizations, including many hospitals (IRS).
2026 contribution limits physicians should know
| Item (2026) | Limit |
|---|---|
| Employee contributions to a 401(k), 403(b) or governmental 457 plan | $24,500 |
| Additional catch-up contribution, age 50 and over (most plans) | $8,000 |
| Higher catch-up contribution, ages 60 to 63 | $11,250 |
| IRA contribution limit | $7,500 |
| Roth IRA income phase-out, single filers | $153,000 to $168,000 |
| Roth IRA income phase-out, married filing jointly | $242,000 to $252,000 |
Source: IRS, IR-2025-111. Many attending physicians earn above the Roth IRA income ranges, which is one reason the choice between pretax and Roth contributions deserves a conversation with your tax professional. For a related decision later in your career, see Roth conversions before retirement.
The plan type alone doesn’t tell you whether a benefit is strong. Review employer contributions, vesting, investment choices, plan expenses, Roth and pretax options, eligibility dates, distribution rules and what happens when you leave.
Review benefits before changing jobs
The U.S. Department of Labor advises finding out what will happen to your retirement benefits before you change jobs, and knowing your options for savings left in a former employer’s plan (DOL). Before accepting a new position, ask when health coverage begins, whether you’ll lose unvested employer contributions, which disability and life insurance benefits will end, whether the new retirement plan is comparable, and whether pay depends on productivity or bonuses. Don’t compare offers on base salary alone.
4. Insurance and asset protection should protect the plan
For most physicians, future earning capacity is the largest financial resource they have. An illness or injury that affects your ability to practice affects far more than this year’s income.
Disability coverage, especially for surgeons and procedural specialists
Employer disability coverage can be useful, but the terms matter. Review the definition of disability (whether it refers to your own occupation or specialty, or to any occupation), the benefit amount, waiting period, benefit duration, exclusions, portability and the tax treatment of benefits. Surgeons and other physicians whose work depends on fine motor skills should look especially closely at how a policy defines their occupation.
Life insurance and beneficiaries
Life insurance needs often change after marriage, children, a home purchase, practice ownership or a large increase in assets. Coordinate coverage with income replacement needs, debts, education goals, business obligations, existing savings and beneficiary designations. Our guide to life insurance for high-income earners goes deeper.
Liability and asset protection
Physicians carry professional liability exposure. Malpractice coverage, personal umbrella liability coverage, how accounts are titled and how a practice is structured all affect how exposed your personal assets are. These are legal and insurance questions as much as financial ones, so coordinate them with your attorney and insurance professional. An advisor’s job is to spot the gaps and bring the right professionals together.
5. Tax planning needs coordination, not isolated tactics
Tax planning for doctors gets more complicated as income, compensation, investments and ownership interests grow. A financial advisor shouldn’t replace a qualified tax professional, but should help identify decisions that need tax analysis and coordinate with your CPA. These include pretax versus Roth contributions, bonus or productivity pay, estimated tax payments, practice income and ownership interests, charitable giving, investment gains and losses, retirement account distributions, relocating to another state, and the sale of a practice interest.
Tax coordination is more useful before a transaction than after it. A physician considering a practice buy-in should understand the cash needed, financing terms, business structure and possible tax consequences before signing. The advisor, tax professional and attorney may each look at a different part of the decision. Our article on the benefits of tax planning explains more.
Stoic Wealth Advisors and LPL Financial do not offer tax or legal advice. Please consult qualified tax and legal professionals regarding your individual situation.
6. Match investment risk to goals, time and liquidity
A portfolio shouldn’t be based only on age or on how comfortable you feel with market declines. Investor.gov explains that asset allocation depends in part on your time horizon and risk tolerance (Investor.gov). A good process also considers how much money must stay accessible and how much loss your situation can absorb.
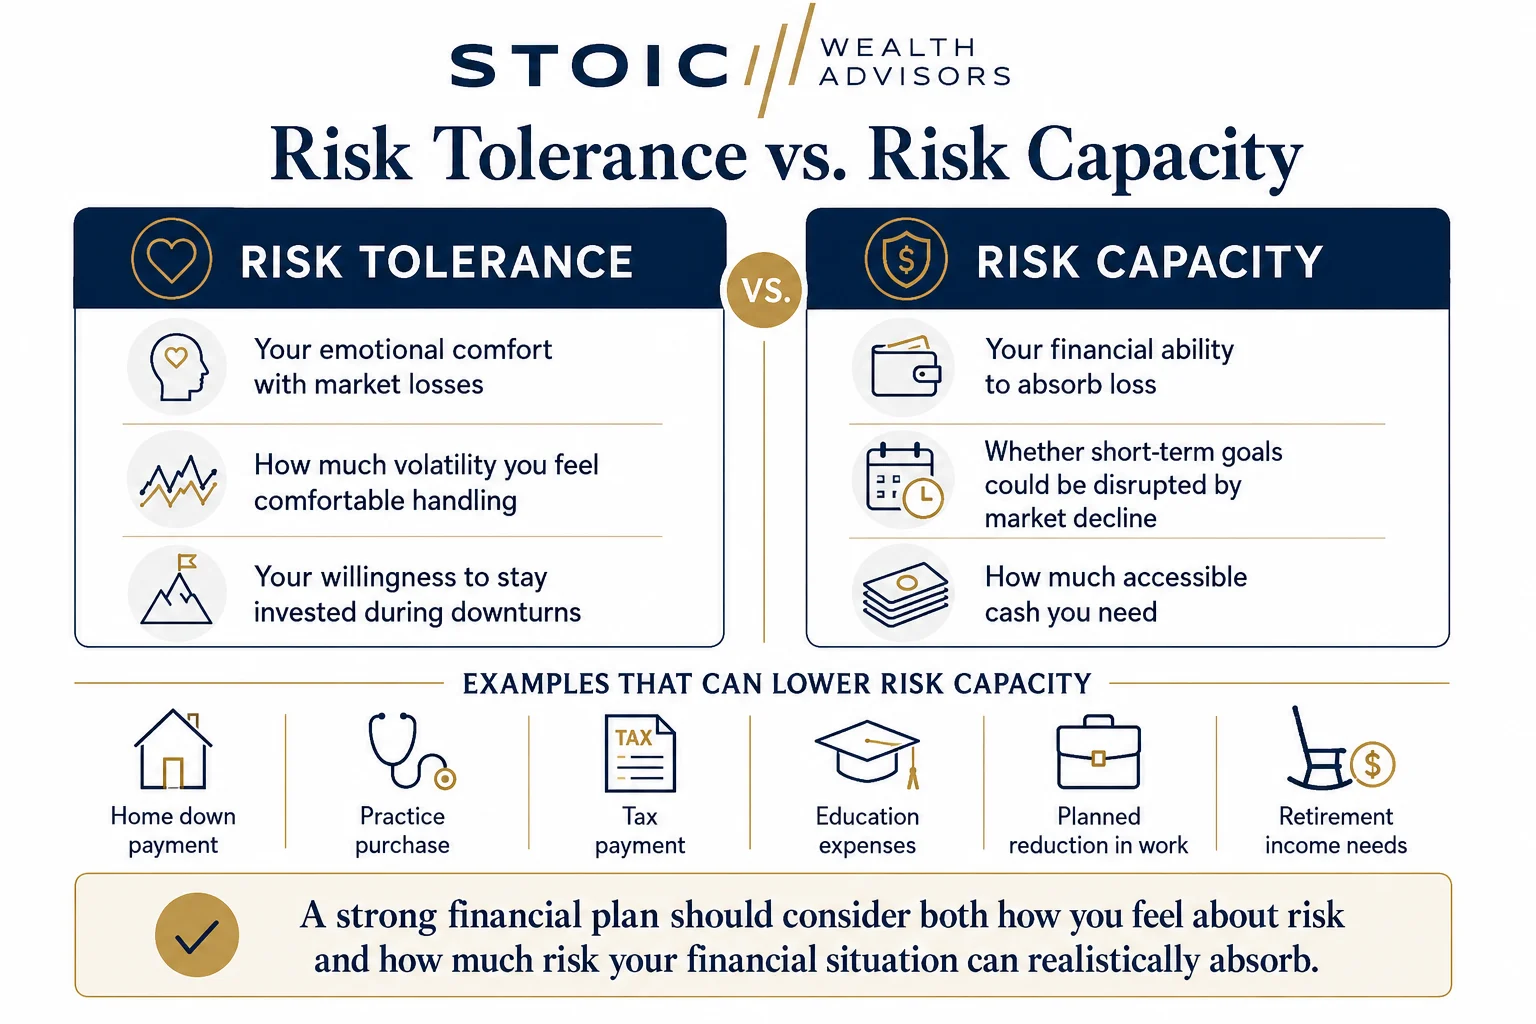
Investment risk should reflect both emotional comfort with market losses and the financial ability to absorb loss without disrupting important goals.
Separate risk tolerance from risk capacity
Risk tolerance is your willingness to accept investment losses. Risk capacity is how much loss your finances can absorb without derailing important goals. A physician may be comfortable with market risk yet have little capacity for loss if the money is needed soon for a down payment, a practice purchase, a tax bill, education costs or a planned reduction in hours. The reverse also happens. A plan that ignores your discomfort may be hard to stick with in a downturn.
Give each goal its own time horizon
Retirement savings, emergency reserves, a home purchase and a practice investment don’t share a timeline. Money needed soon shouldn’t be invested the same way as money meant for retirement decades away.
Investing involves risk, including possible loss of principal. Asset allocation and diversification may help manage certain risks, but they do not guarantee a profit or protect against all losses.
7. Retirement timing depends on more than an account balance
Because physicians often start full earnings late, there may be fewer high-income years to contribute. That doesn’t rule out a comfortable retirement, but it makes savings rates, spending, timing, benefits and investments more closely connected.
A retirement projection should consider expected spending, retirement age, Social Security and other income, workplace accounts, taxable savings, healthcare before and after Medicare eligibility, debt, investment risk, inflation, longevity, family or legacy goals, and the possibility of cutting back to part-time before stopping completely. A useful plan shows which assumptions matter most and what you can adjust, such as working longer, phasing into part-time work, saving more in peak years, reducing planned spending or changing where you retire.
8. Estate planning grows in importance with your assets
As your net worth, family and practice interests grow, so does the importance of up-to-date wills, trusts, powers of attorney, healthcare directives and beneficiary designations. These documents should work together with your insurance and account titling. Estate documents are prepared by attorneys, and an advisor helps make sure the financial pieces match. See our estate planning page for how we coordinate this work.
Physician financial review worksheet
Use this before a new job, a major decision, a change in income, a family event or a retirement transition.
| Review question | Your notes |
|---|---|
| What is changing in my career or family life? | |
| How will my reliable income change? | |
| Which expenses will become fixed or recurring? | |
| How much accessible cash will I need? | |
| Do my student loans need a new strategy, and could PSLF apply? | |
| Which workplace benefits will begin, change or end? | |
| Are there gaps in disability, life or liability coverage? | |
| Will the change affect my taxes or need professional coordination? | |
| Does my investment strategy still match my time horizon and liquidity needs? | |
| How does the decision affect my intended retirement date? | |
| Which beneficiary designations or estate documents should be reviewed? | |
| Which decision must be made first? |
How to choose a financial advisor as a physician
You don’t need an advisor who works only with doctors, but you do need one who understands how medical training, income progression, benefits, insurance, practice ownership and retirement timing affect a plan. When you compare advisors, look for:
- Experience with physicians. Ask whether they’ve worked with people in your situation, including practice owners if you run a clinic. You shouldn’t have to explain how residency, RVUs or call pay work.
- An understanding of physician-specific risks. Education debt, practice expenses, liability exposure and the need for strong disability coverage should be part of the conversation from the start.
- Attention to personal goals, not just professional ones. A good advisor helps you step back from medicine and plan for family, education, travel, a possible practice or business, and the timing of retirement.
- Trust and transparency. Ask how they’re paid, what services you’ll receive and how they explain trade-offs. You can look up an advisor’s registrations and history on FINRA BrokerCheck.
For more questions to ask, read 4 signs to look for when choosing a financial advisor.
Frequently asked questions about financial planning for physicians
When should a physician start financial planning?
Ideally during residency or fellowship. Early decisions about student loans, emergency reserves and disability coverage shape what’s possible once attending income begins, and it’s easier to set a savings habit before lifestyle costs rise.
Should doctors pay off student loans or invest first?
It depends on interest rates, whether Public Service Loan Forgiveness could apply, employer retirement contributions, cash reserves and upcoming expenses. Many physicians do both, for example by capturing an employer match while repaying debt on a set schedule.
How much can a physician contribute to a 401(k) or 403(b) in 2026?
The IRS employee contribution limit for 401(k), 403(b) and governmental 457 plans is $24,500 in 2026, plus an $8,000 catch-up for most participants age 50 and over and an $11,250 catch-up for ages 60 to 63.
What insurance do physicians need?
Most physicians review disability insurance, life insurance, malpractice coverage and personal umbrella liability coverage. The right amounts depend on income, specialty, family, debts and existing employer coverage.
Is financial planning different for surgeons?
The building blocks are the same, but surgeons often pay closer attention to how disability insurance defines their occupation, to liability exposure, and to a shorter or more physically demanding career that may affect retirement timing.
Do physicians need a financial advisor who specializes in doctors?
Not necessarily. What matters is experience with physicians’ situations, a clear explanation of how the advisor is paid, and the ability to coordinate with your tax and legal professionals.
Adding clarity at every stage of your medical career
Financial planning for physicians isn’t a one-time calculation, and physician financial planning works best when it is reviewed at every career change. It’s an ongoing process that connects today’s decisions with the career and life you’re working toward. At Stoic Wealth Advisors, we start by understanding your goals, circumstances, liabilities, resources and risk tolerance before making recommendations. Luke Rudolph educates plan participants at Yavapai Regional Medical Center and several physician care clinics in the Prescott area. Learn more about how we work with physicians in Prescott and Scottsdale, who we serve and the planning areas we cover.
When you’re ready to talk through your career stage and priorities, schedule time to meet with Luke or call 928-224-3160.
This material is for general educational purposes only and is not individualized investment, tax, legal or insurance advice. Investing involves risk, including possible loss of principal. No investment strategy or risk-management technique can guarantee a return or eliminate risk in every market environment. Stoic Wealth Advisors and LPL Financial do not offer tax or legal advice. Please consult qualified tax and legal professionals regarding your individual situation. Securities and advisory services offered through LPL Financial, a registered investment advisor, member FINRA/SIPC. Stoic Wealth Advisors and LPL Financial are separate entities.